Mortgage Broker on the Northshore
Mandeville, Covington, Slidell & St. Tammany Parish
Across the Lake, a Different Kind of Search
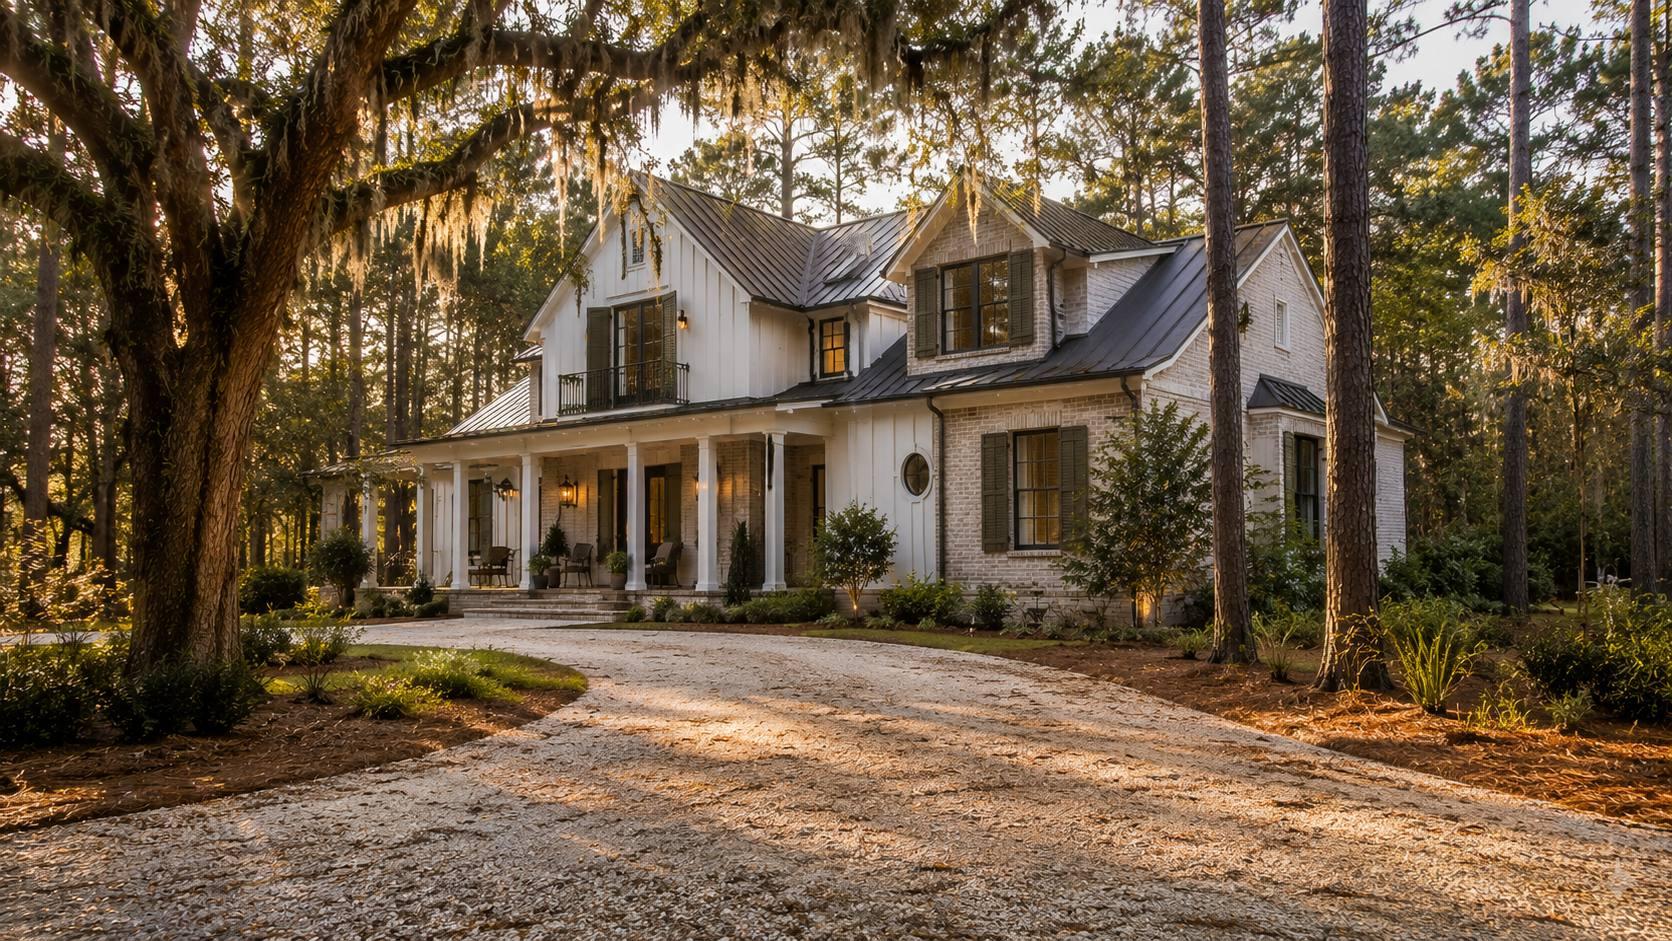
Most Northshore buyers want room: a bigger lot, a newer house, a school they’ve already researched. St. Tammany gives them a lot of options. In Mandeville, Old Mandeville’s lakefront cottages and shaded streets sit a few minutes from planned subdivisions with pools, walking paths and HOA-maintained entrances. Covington pairs a walkable historic downtown with established neighborhoods along the Bogue Falaya and Tchefuncte, and the further north you go toward Folsom, the more listings have acreage, barns and pasture.
Slidell has its own feel. Olde Towne has older homes near the railroad, and canal-front neighborhoods let you keep a boat behind the house. Brick ranches and newer subdivisions fill in the middle. Madisonville and Abita Springs round things out with small-town lots and plenty of new construction on the edges.
Many of my Northshore clients commute across the Causeway or the I-10 twin span. Others are moving over from the Southshore for the first time. Either way, the search here often includes a builder contract, a septic system or a waterfront elevation question, and each of those needs to be planned into the financing early.
Who I Help Here
Local Loan Considerations
Rivers, the lake and a lot of new construction shape Northshore loans. These come up most.
Flood Zones & Flood Insurance
On the Northshore, flood risk comes from two directions. Rivers like the Bogue Falaya, Tchefuncte and Pearl can rise inland, and the lake and storm surge affect lower areas around Slidell and the lakefront. A home that looks high and dry may still be in a mapped zone.
On new construction, the builder’s elevation certificate can change the flood premium a lot, so I ask for it before closing instead of after.
Homeowners Insurance & Qualifying
Homeowners coverage counts in your monthly payment, so it caps how much house you qualify for. A brand-new roof and modern construction can help with insurers, while an older roof or a waterfront location can push the premium the other way.
On acreage, ask your agent how outbuildings, barns and detached shops are covered. Then we size the loan around real quotes, not estimates.
Property Types
New construction is common here, and timing a builder’s completion date against a rate lock and appraisal takes planning. Rural and acreage homes may have a well and septic, which lenders want inspected, and very large tracts can limit which programs fit.
Some outlying parts of the parish may qualify for USDA financing. Eligibility depends on the exact address, so we check each one.
A Refined Lending Experience
Three conversations. One closing.
Consult
A confidential conversation about your goals, timeline, and what your full picture actually looks like.
Structure
We map the program, the rate, the down payment, and the closing math — then I shop it across the network.
Close
Tight coordination from underwriting to keys. You'll know what's happening, every week, in plain English.
Common Questions
Can I get a mortgage on a home with acreage in Covington or Folsom?
Yes, but the amount of land, the outbuildings and whether the property is primarily residential all affect which programs fit. Conventional, FHA, VA and sometimes USDA can work on acreage. Very large or income-producing tracts may need a different approach. Send me the listing and I’ll tell you which lenders will look at it.
How does buying new construction in a St. Tammany subdivision work with my loan?
I get you pre-approved before you sign the builder contract, then plan the rate lock and appraisal around the expected completion date. Builders often have a preferred lender. You’re free to use your own, and comparing their offer against what my 80+ lenders can do is worth the time.
Is any of St. Tammany Parish eligible for USDA loans?
Some outlying areas may be. USDA eligibility is set by address and the maps get updated, so the only reliable answer is to check the specific property. If it’s eligible and your household income fits the program limits, USDA can be a strong zero-down option.
What should I know about financing a waterfront home in Slidell?
Expect flood insurance to be required and to be a big part of your monthly payment. Bulkheads, docks and the home’s elevation all affect appraisal and insurance. Get the elevation certificate and an insurance quote early, because they determine how much house the payment supports.
I’m moving from New Orleans to Mandeville. Can I buy before I sell?
Often, yes. Depending on your income and equity, we can qualify you while carrying both payments, use a bridge-style structure, or count a pending sale. The right answer depends on how much equity you have and how much risk you want to take on, and we’ll talk through both before you list.
Making the Move Across the Lake?
Whether it’s a new build in Covington or a canal-front home in Slidell, let’s line up the financing before you fall for the house.