Mortgage Broker in Baton Rouge
East Baton Rouge, Ascension & Livingston Parishes
A Capital City With Suburbs in Every Direction
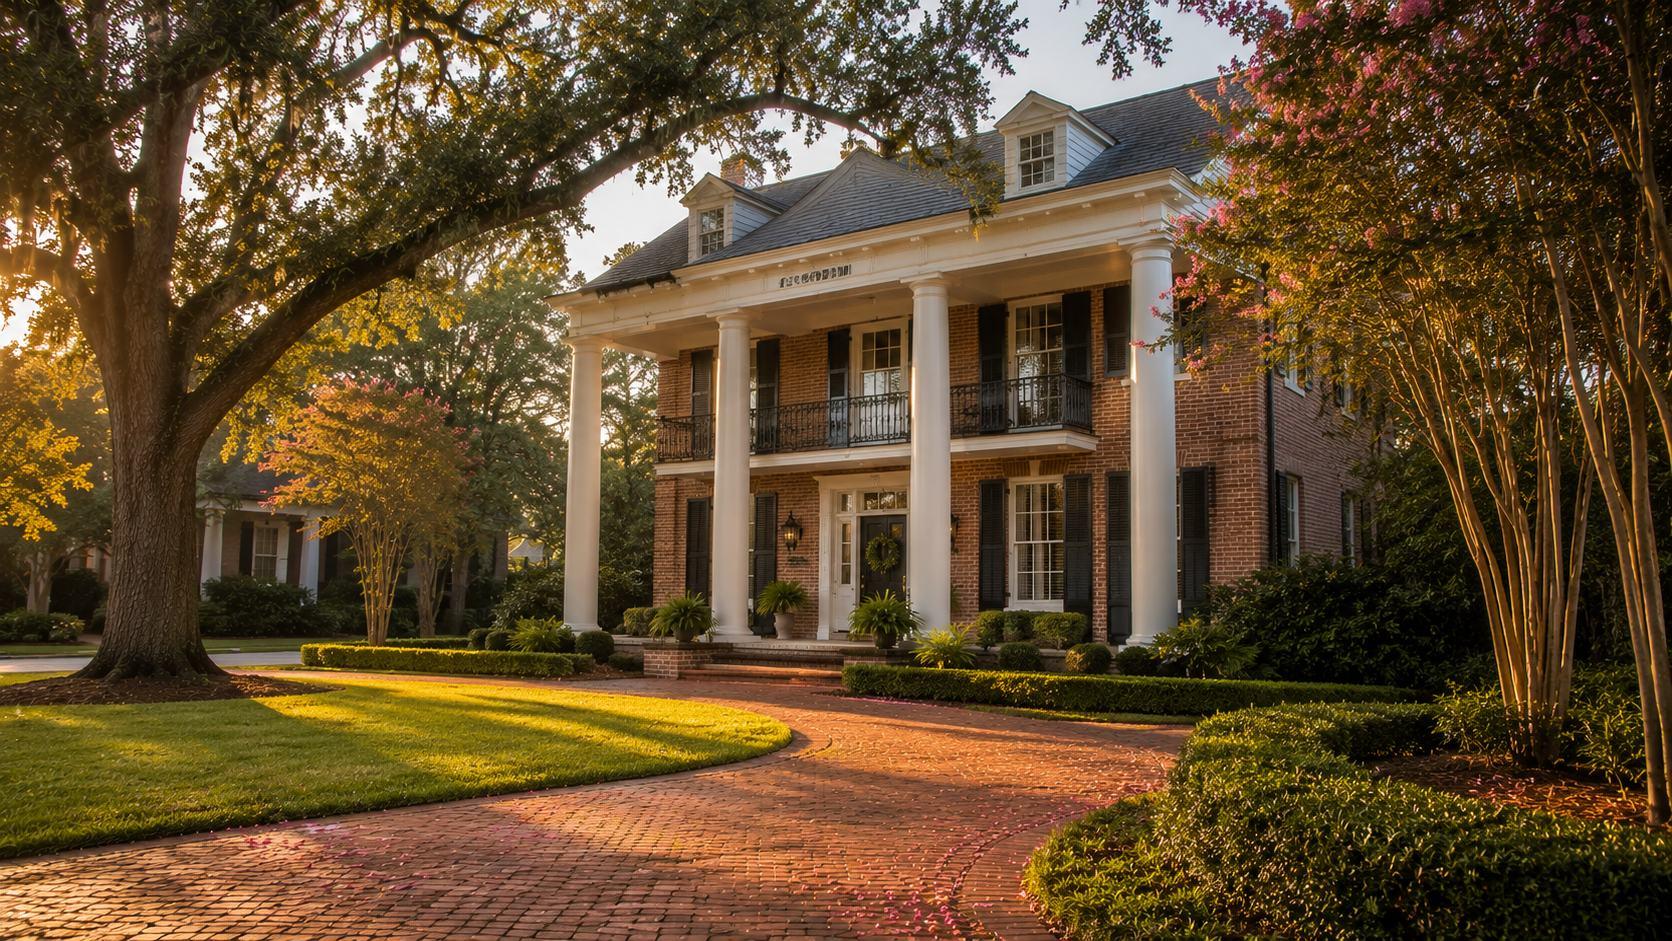
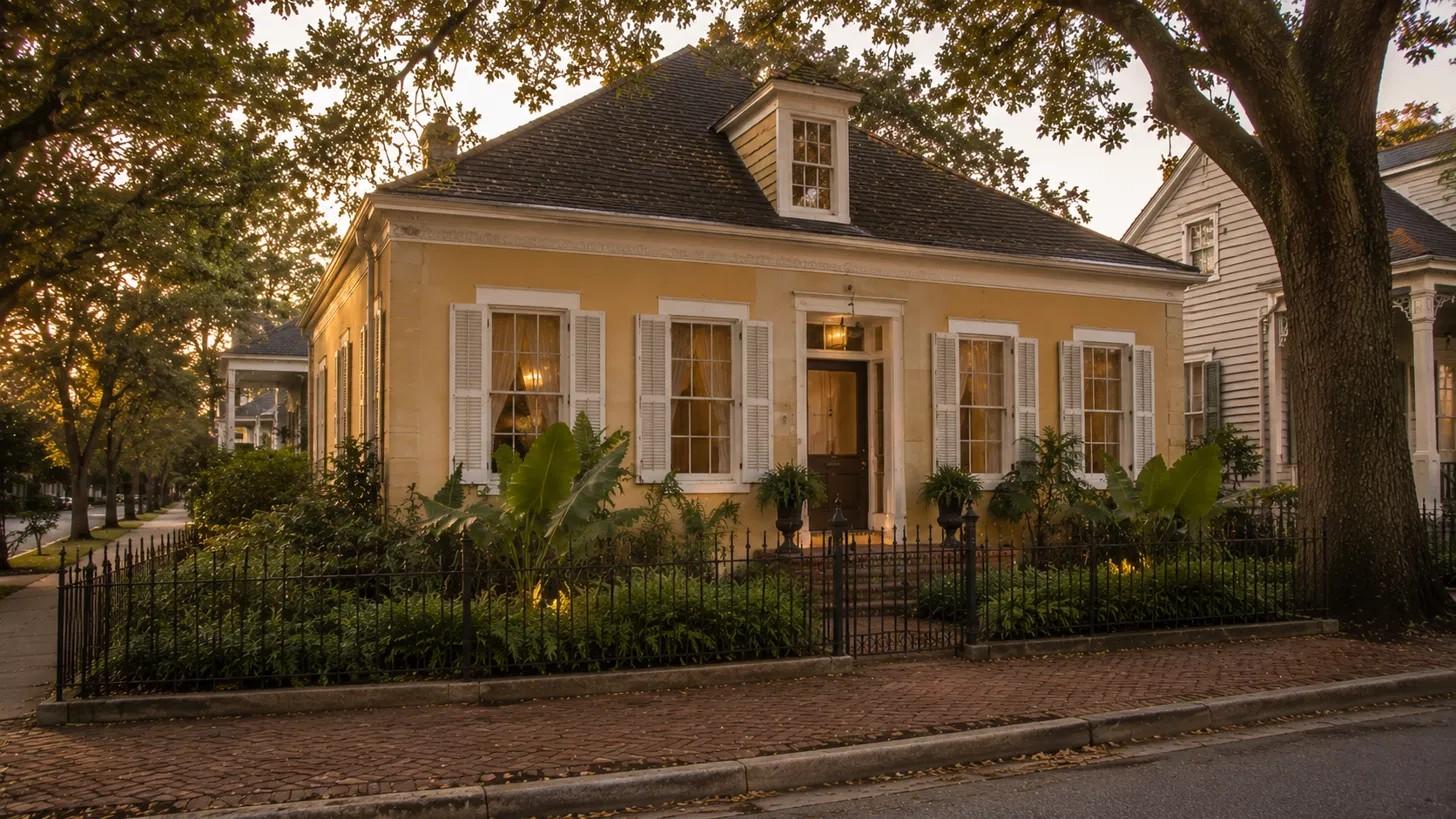
Baton Rouge buyers have a wide range to choose from. Close to downtown, Spanish Town and Beauregard Town have small historic cottages next to state offices. The city’s own Garden District and the streets around it are full of brick and wood-frame homes from the early and middle twentieth century. Mid City has been drawing renovators to its bungalows, and Southdowns and the neighborhoods near the lakes offer established, tree-lined streets.
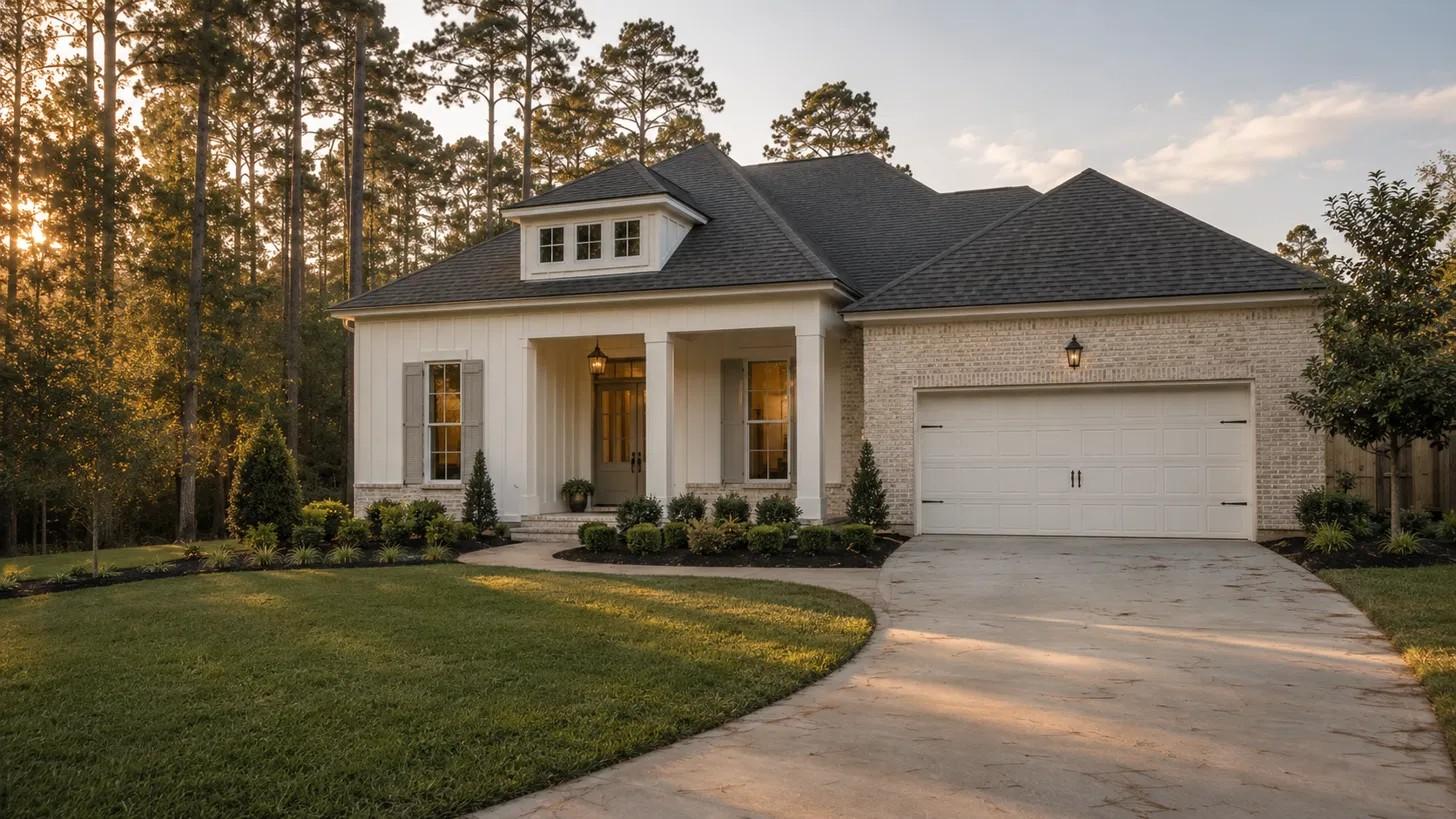
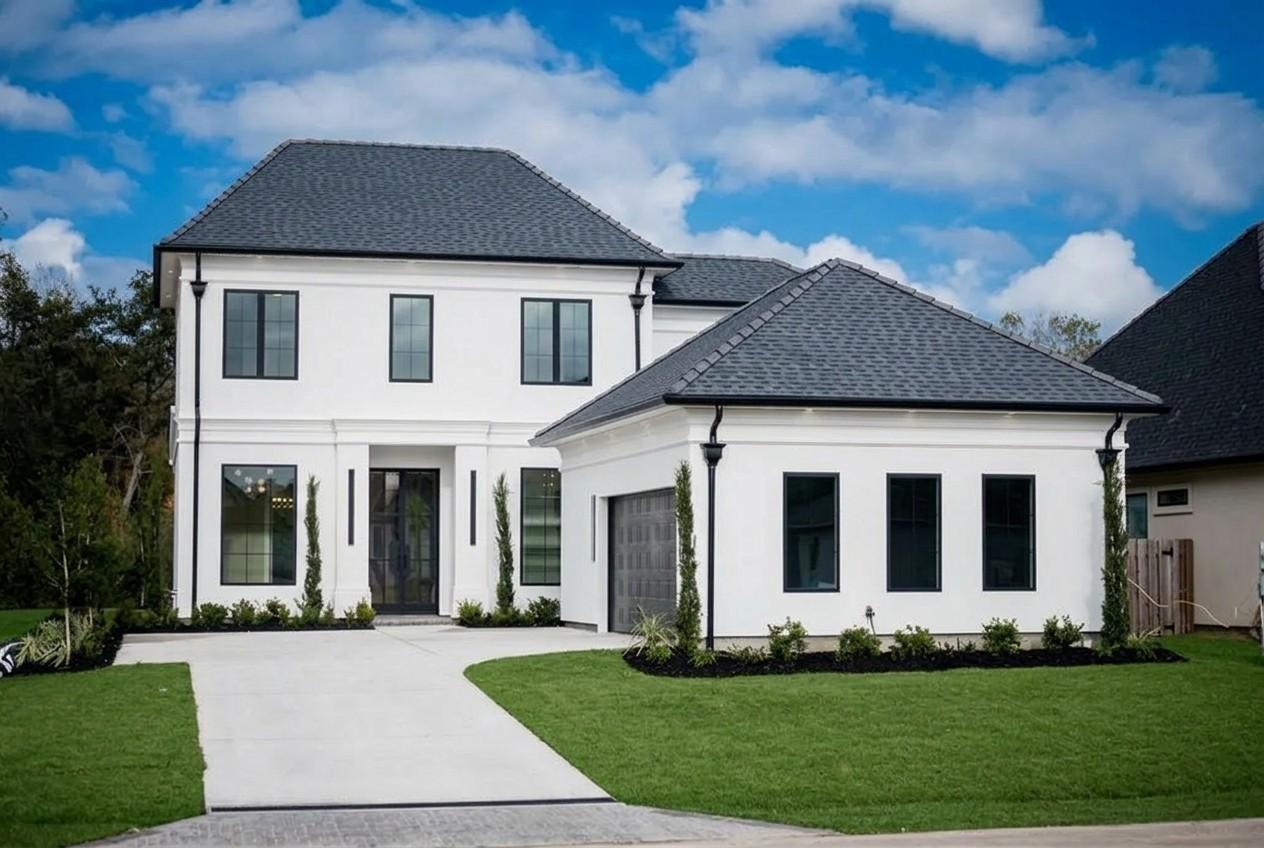
Around LSU, the market leans toward rentals: older houses split for students, small multifamily buildings and condo complexes that investors buy with lease-ups in mind. Further out, Prairieville and the rest of Ascension Parish are known for newer subdivisions. Denham Springs and Walker in Livingston Parish attract buyers who want more house for the money, and Zachary and Central offer suburban lots north of the city.
The workforce here is part of the picture too. State employees, university staff and plant workers on rotating shifts all document income differently, and building a file that shows overtime, shift differentials or a recent job change correctly is as important as the property.
Who I Help Here
Local Loan Considerations
Baton Rouge sits above the coast but is laced with rivers and low ground. Plan for these.
Flood Zones & Flood Insurance
The 2016 flood showed that homes outside mapped high-risk zones can still flood, especially along the Amite and Comite rivers and throughout Livingston and Ascension. Flood insurance is required in FEMA special flood hazard areas, and buying it voluntarily elsewhere is worth considering.
Ask whether the home has flooded before and whether it was raised or rebuilt afterward. Those answers affect the premium and the appraisal.
Homeowners Insurance & Qualifying
Insurance costs are rising in Baton Rouge too, and your homeowners premium goes into the payment lenders qualify you on. Roof age, construction type and claims history all move the quote.
For first-time buyers working with a tight budget, the gap between an estimated premium and a real quote can change which houses are affordable. We get real quotes during the option period so there are no surprises at closing.
Property Types
Condos near campus have to pass the lender’s project review, and complexes with a lot of investor ownership or ongoing litigation can narrow your options. Older homes split into student units may be legally two-to-four units, or may not be, and that determines how they’re financed.
In the suburbs, new construction and HOA neighborhoods dominate, which brings builder timelines and HOA dues into the qualifying math.
A Refined Lending Experience
Three conversations. One closing.
Consult
A confidential conversation about your goals, timeline, and what your full picture actually looks like.
Structure
We map the program, the rate, the down payment, and the closing math — then I shop it across the network.
Close
Tight coordination from underwriting to keys. You'll know what's happening, every week, in plain English.
Common Questions
Can I buy a rental near LSU using the property’s income to qualify?
Yes. A DSCR loan qualifies you on the property’s rent rather than your personal income, which works well for investors with complicated tax returns. Student-oriented properties need a realistic rent figure and, for condos, a building the lender will approve, so we vet both before you make an offer.
Can I buy a condo for my kid at LSU and have them live in it?
Often, yes. Depending on how it’s structured, a parent-purchased condo is usually financed as a second home or an investment property, and each option has different down payment and occupancy rules. The condo complex also has to meet lender guidelines, so we check that early.
How do lenders count overtime and shift pay for plant workers?
Lenders generally want to see a consistent history of overtime, shift differentials or bonuses before they count them, and they average it over time. If your pay recently changed or you switched employers, how the file is documented makes a big difference. That’s where shopping across many lenders helps.
Do I need flood insurance in Denham Springs or Prairieville?
If the home is in a FEMA special flood hazard area, your lender will require it. Even outside those zones, many homeowners in Livingston and Ascension choose to carry flood insurance after 2016. We check the exact flood zone and get a quote so you can make that decision with real numbers.
Is it better to buy new construction in Ascension or an older home in Baton Rouge?
It depends on your priorities. New construction usually brings a newer roof and systems, which can help with insurance, plus builder timelines and HOA dues. Older homes in town may have more character and a shorter commute but need more inspection work. I can pre-approve you for both so you can compare.
Buying in the Baton Rouge Area?
Campus rental, Mid City bungalow or a new build in Prairieville — tell me what you’re looking at and I’ll map out the loan.