Mortgage Broker in New Orleans
Orleans Parish, Metairie & Jefferson Parish
Financing a City Built One Block at a Time
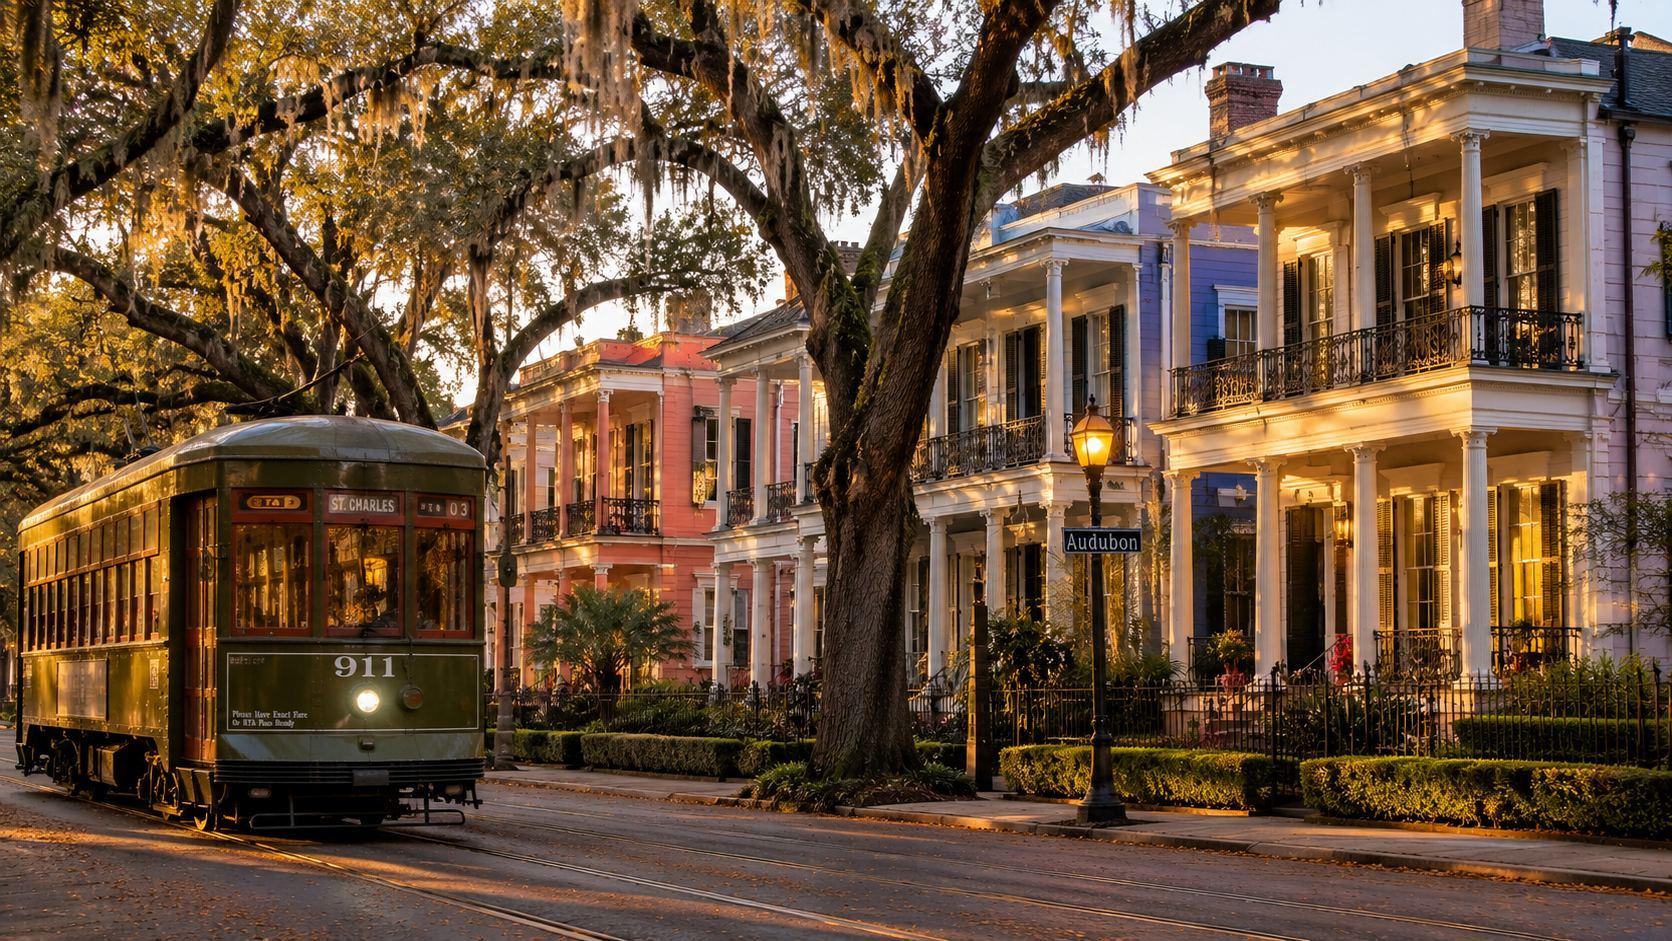
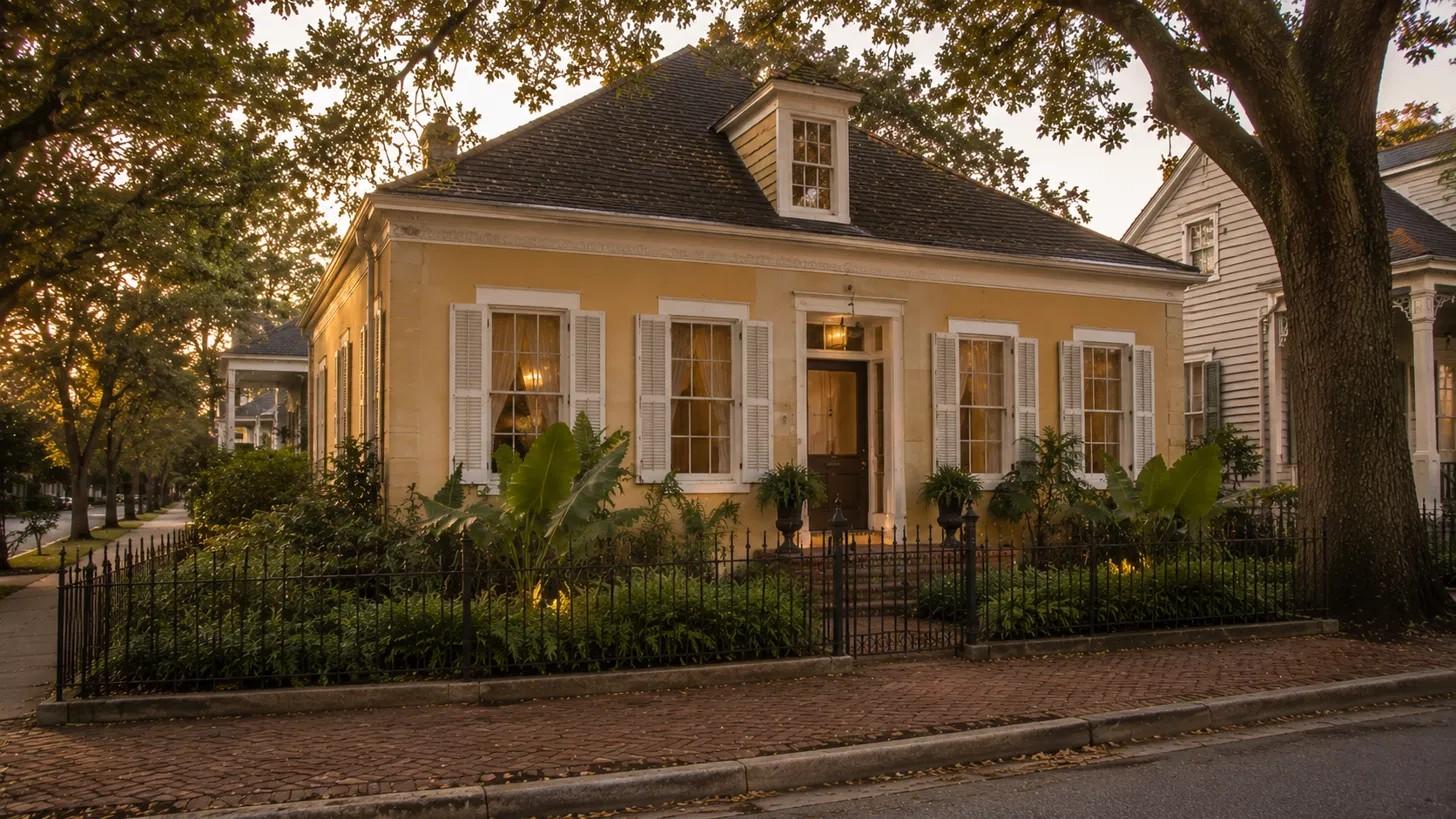
New Orleans housing changes character every few streets. Uptown and the Irish Channel are dense with shotgun doubles, camelbacks and raised center-hall homes, many of them a century old or more. Mid-City and Bayou St. John mix renovated doubles with bungalows, while the Marigny and Bywater lean toward Creole cottages and fully gutted renovations. Gentilly and much of New Orleans East are mid-century slab ranches, and Lakeview is a patchwork of original brick homes and newer houses rebuilt high off the ground. Across the river, Algiers gives buyers more yard and a quieter pace.
Over the parish line, Metairie and the rest of Jefferson Parish offer a different rhythm: Old Metairie’s established streets, ranch and split-level homes on slab through the middle of the parish, and River Ridge, Harahan and Kenner for buyers who want space close to the airport and the river.
My office is in Metairie, so this is the market I know best. A renovated double, a raised Lakeview rebuild and a slab ranch in Gentilly each bring different appraisal, insurance and underwriting questions, and I sort those out before you write an offer.
Who I Help Here
Local Loan Considerations
Below sea level, older housing stock and a hurricane coast all show up in the loan file. Here’s what to plan for.
Flood Zones & Flood Insurance
Large parts of Orleans and Jefferson Parish sit in FEMA special flood hazard areas, and the designation can change from one side of a street to the other. If the home is in a mapped zone, your lender will require flood insurance.
An elevation certificate often matters as much as the zone itself. A raised home and a slab home on the same block can carry very different premiums, so I ask for the elevation certificate early.
Homeowners Insurance & Qualifying
Your homeowners premium is part of your monthly housing payment, so it directly affects how much you qualify for. In New Orleans, wind and hurricane coverage, the deductible structure and the age of the roof all affect what a policy costs. Some older homes have trouble getting coverage at all.
I have buyers get a real insurance quote while we’re still negotiating, so the payment we qualify you on is the payment you’ll actually make.
Property Types
Shotgun doubles are two-unit properties, and that opens up owner-occupied two-unit financing, where rent from the other side can help you qualify. Historic district rules can limit exterior renovation work, and condos in converted buildings need to clear the lender’s project review.
Older homes with original wiring, piers or past water damage may need a renovation loan or repairs negotiated before closing.
A Refined Lending Experience
Three conversations. One closing.
Consult
A confidential conversation about your goals, timeline, and what your full picture actually looks like.
Structure
We map the program, the rate, the down payment, and the closing math — then I shop it across the network.
Close
Tight coordination from underwriting to keys. You'll know what's happening, every week, in plain English.
Common Questions
Can I buy a New Orleans double and live in one side?
Yes. A double is a two-unit property, so you can finance it as an owner-occupant with conventional, FHA or VA programs. Projected rent from the other side can often be counted toward your qualifying income, which makes a double one of the most common ways people buy their first home in the city.
Can I finance a short-term rental in New Orleans?
New Orleans regulates short-term rentals closely, and the rules have changed more than once. Before you buy with STR income in mind, confirm the property’s permit eligibility with the city. I usually underwrite New Orleans investment property on long-term rent so the deal still works if a short-term permit isn’t available.
Do I need flood insurance if the home is in Metairie?
If the property is in a FEMA special flood hazard area and you have a federally backed or regulated mortgage, the lender will require flood insurance. Much of Jefferson Parish is mapped that way, but it depends on the exact address, so we check the flood zone and get a premium quote before you commit.
Does a historic district affect my mortgage?
It doesn’t change which loan programs you can use, but it can change your renovation plans. Exterior work in local historic districts usually needs approval, which can affect your timeline and your rehab budget. If you’re using a renovation loan, we build that review time into the plan.
Why do two similar homes in Lakeview have such different payments?
Usually because of insurance. A home rebuilt high off the ground can have a very different flood premium than an original slab home a few doors down, and roof age and construction type move the homeowners premium too. Since insurance is part of your monthly payment, those differences change what you qualify for.
Buying in New Orleans or Metairie?
Send me the address or the neighborhood. I’ll tell you what the loan, the flood zone and the insurance look like before you write the offer.