Mortgage Broker in Lafayette
Lafayette Parish, Youngsville, Broussard & Acadiana
Acadiana Homes, Acadiana Paychecks
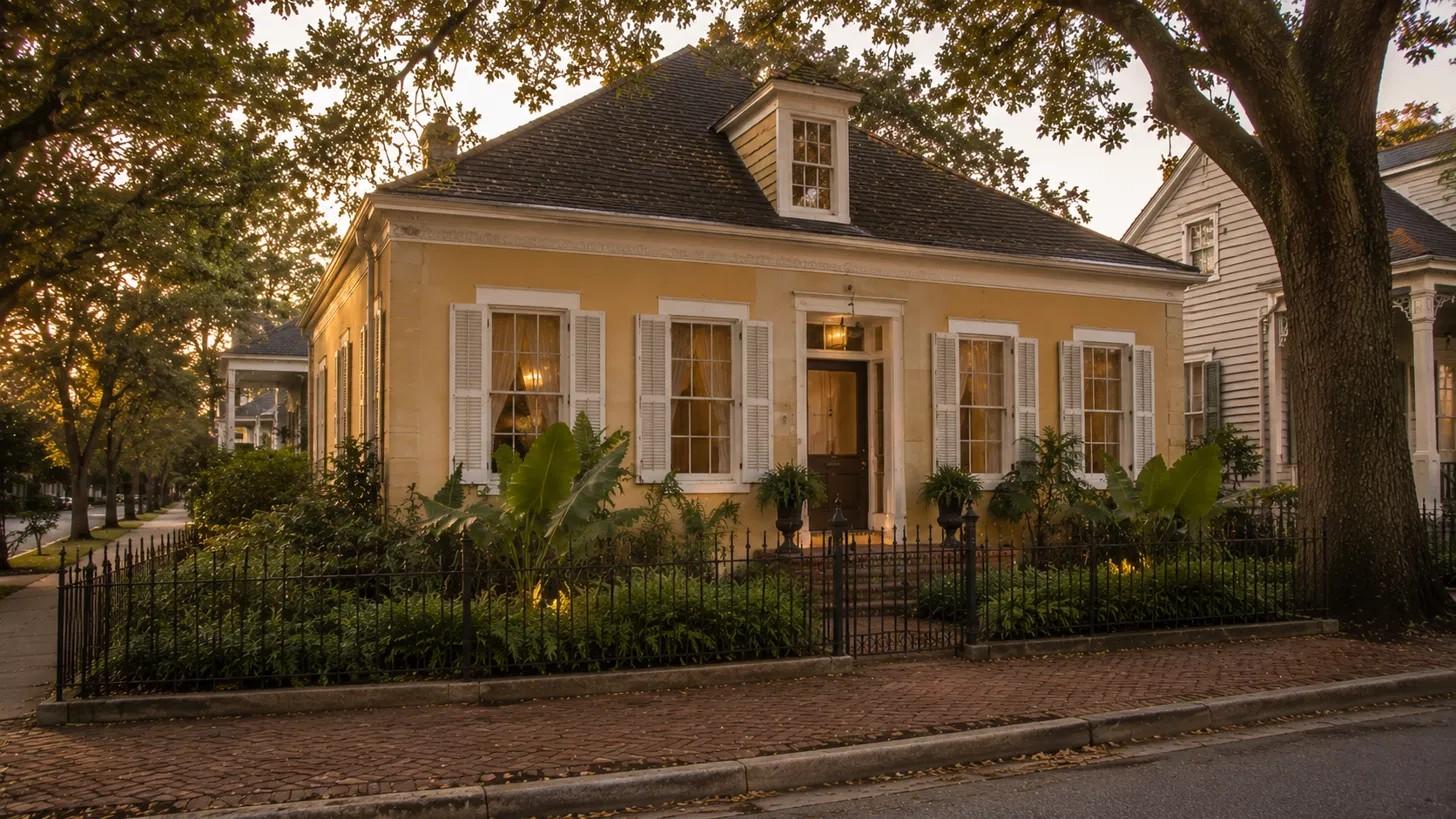
Lafayette doesn’t look like New Orleans, and buyers here aren’t shopping for the same houses. Near UL Lafayette, the Saint Streets are full of cottages and bungalows with deep porches, popular with professors, young families and landlords renting to students. The Oil Center and the neighborhoods around it have mid-century brick ranches close to the medical district. River Ranch is a planned, walkable neighborhood with traditional Acadian-style architecture.
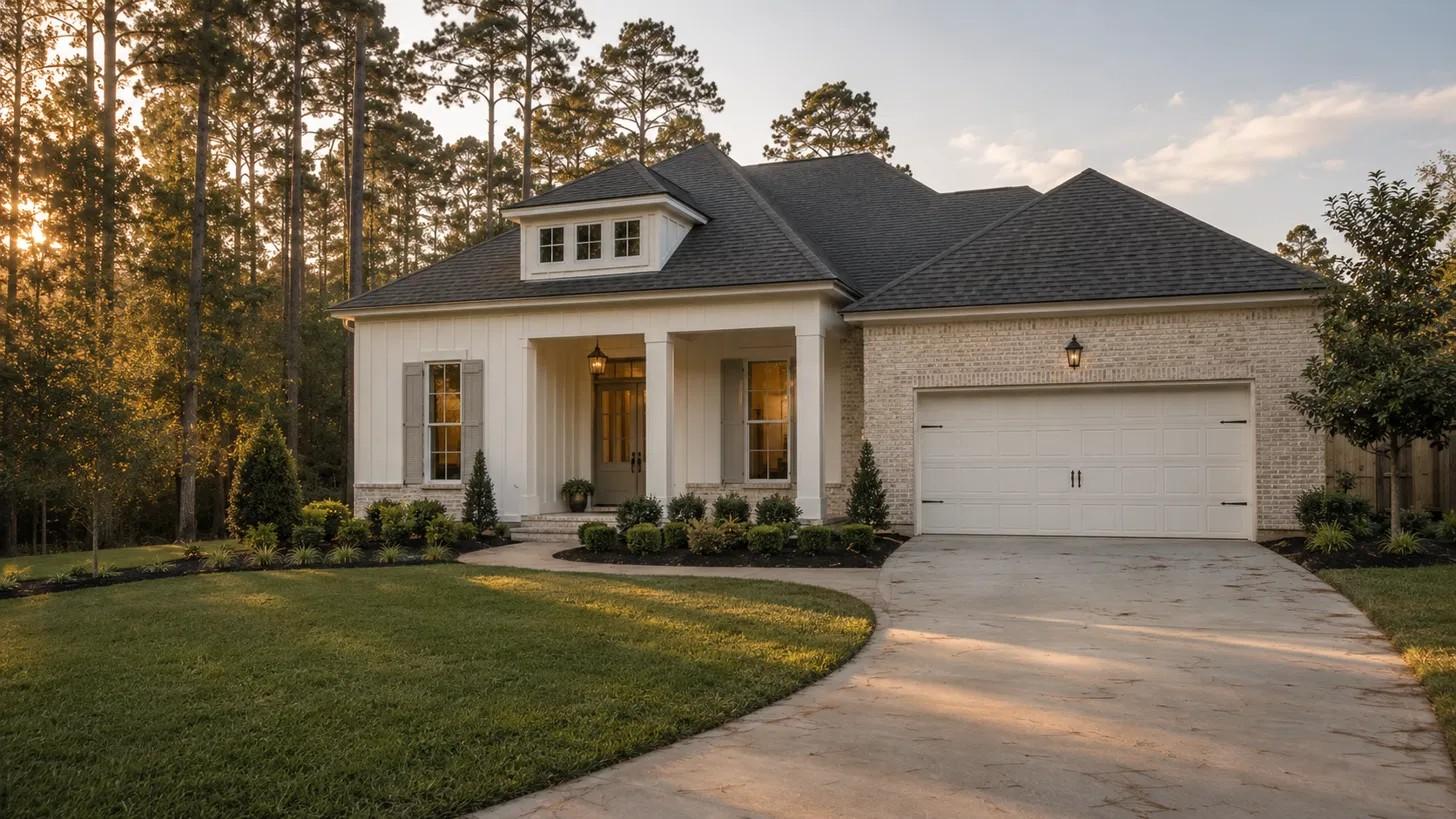
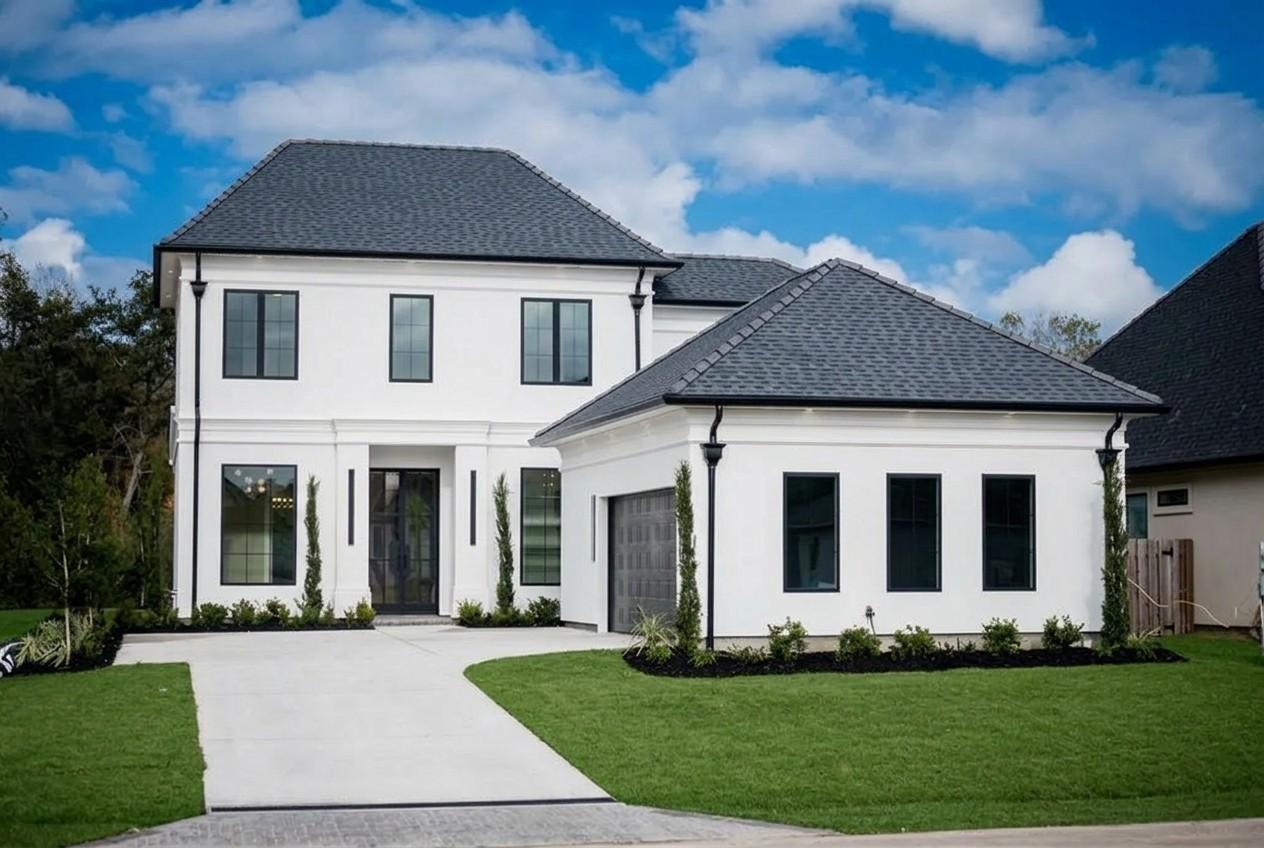
A lot of the new construction is south of the city. Youngsville and Broussard are lined with brick subdivisions and newly built homes, while Carencro and Scott offer more space on the north and west sides. Head out into the surrounding parishes and you’ll find raised Acadian cottages, homes on acreage and properties along the Vermilion River and its coulees.
Income here often doesn’t fit a bank’s checklist. Offshore rotations, oilfield service contracts, family businesses and 1099 work are normal in Acadiana, and a lender who only reads W-2s will miss most of what you earn. Matching the right documentation path to how you actually get paid is where a broker earns their keep.
Who I Help Here
Local Loan Considerations
Flat land, coulees and an energy-driven economy shape loans in Acadiana. Here’s what matters most.
Flood Zones & Flood Insurance
Much of Lafayette Parish drains through the Vermilion River and a network of coulees, and heavy rain can flood neighborhoods that aren’t near open water. FEMA maps here have been revised over time, so check the current zone for the exact address.
If the home is in a special flood hazard area, flood insurance is required. Outside those areas, flood history and the slab’s elevation should still factor into whether you buy coverage.
Homeowners Insurance & Qualifying
Lafayette is inland, but hurricanes still reach it, and insurers price wind risk accordingly. Your homeowners premium is part of the monthly payment lenders qualify you on, so a higher quote reduces your purchase budget.
Newer brick homes with recent roofs usually quote well. Older raised cottages and rural properties with outbuildings take more shopping, so get those quotes early.
Property Types
New brick construction dominates the south side, which means builder contracts, completion timelines and sometimes HOA dues. Rural properties may have private wells, septic systems and acreage that affect appraisal and program eligibility. Some areas outside the city may qualify for USDA, depending on the address.
Older homes near campus are often bought as rentals, so knowing whether they’re legally one unit or several matters.
A Refined Lending Experience
Three conversations. One closing.
Consult
A confidential conversation about your goals, timeline, and what your full picture actually looks like.
Structure
We map the program, the rate, the down payment, and the closing math — then I shop it across the network.
Close
Tight coordination from underwriting to keys. You'll know what's happening, every week, in plain English.
Common Questions
I work offshore on a rotation. How do lenders look at my income?
Rotational work is common in Acadiana and lenders can handle it. They look for a steady history with your employer or in your line of work, and they average variable pay like overtime and per diem over time. If you’re a contractor rather than an employee, the documentation is different, so we start by mapping how you’re actually paid.
I’m self-employed in Lafayette. Can I qualify if my tax returns show low income?
Often, yes. Many business owners write off a lot of their income, which hurts them on a traditional loan. Bank statement loans qualify you on deposits instead of taxable income, and DSCR loans qualify an investment property on its rent. I compare those options across lenders to find the one that fits your file.
Can I buy a rental near UL Lafayette with a DSCR loan?
Yes. A DSCR loan underwrites the property’s rent against its payment rather than your personal income. For student-area rentals, we’ll use realistic market rent and confirm the property’s legal unit count, since that affects both the appraisal and which loan programs apply.
Are there USDA-eligible areas around Lafayette?
Some areas outside the city may be. USDA eligibility is determined by address and can change when maps are updated, so we check each property you’re considering. If it qualifies and your household income fits, USDA allows zero down on a primary residence.
Do I need flood insurance in Youngsville or Broussard?
It depends on the exact address. If the property is in a FEMA special flood hazard area, your lender will require it. Outside those zones it’s optional, but heavy-rain flooding in Acadiana doesn’t always follow the map, so many buyers get a quote and decide with the full payment in front of them.
Buying in Lafayette or Acadiana?
Offshore schedule, your own business, or a new build in Youngsville — let’s build the file around how you really earn.